Buying your first home in Maine can feel increasingly difficult when you factor in home prices, mortgage rates, down payments, and closing costs. But many buyers may have access to a financing program specifically designed to make homeownership more attainable.
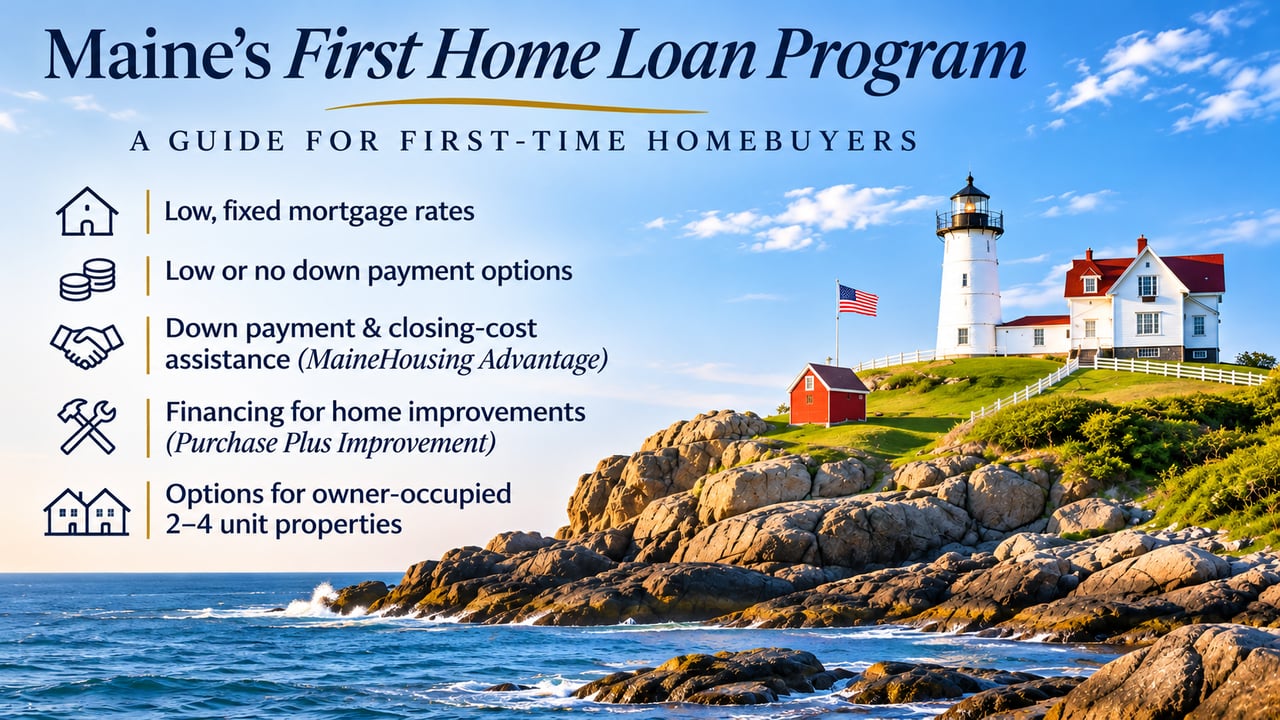
The MaineHousing First Home Loan Program offers qualifying homebuyers low fixed-rate mortgages, options requiring little or no down payment, and potential assistance with down payment and closing costs.
For buyers looking in York, Kittery, Eliot, South Berwick, Ogunquit, Wells, and other Southern Maine communities, understanding this program before beginning a home search could significantly change what is financially possible.
What Is the Maine First Home Loan Program?
The First Home Loan Program is administered by MaineHousing, formally known as the Maine State Housing Authority.
Rather than lending directly to buyers, MaineHousing works through an approved statewide network of banks, credit unions, and mortgage companies. Buyers apply for a First Home Loan through one of these participating lenders.
The program is designed to make purchasing a primary residence more affordable through several potential benefits, including:
- Low fixed mortgage rates
- Zero-point and two-point mortgage options
- Low- or no-down-payment financing options
- Down payment and closing-cost assistance
- Financing for certain home improvements
- Assistance for qualifying owner-occupied multi-unit properties
- Mortgage-payment protection in the event of unemployment
Not every buyer will use every feature, and eligibility depends on the borrower, property, and type of financing.
You May Qualify Even If You Have Owned a Home Before
One of the most important things buyers should understand is MaineHousing's definition of a first-time homebuyer.
You generally qualify as a first-time homebuyer if you have not held an ownership interest in your principal residence during the previous three years.
That means the program is not necessarily limited to people purchasing their first home ever.
Someone who previously owned a home but has been renting for several years, for example, may once again qualify as a first-time buyer.
That can make the First Home Loan Program relevant to a much larger group of Maine buyers than its name initially suggests.
How Much Can You Earn and Still Qualify?
MaineHousing imposes household income limits, but those limits are considerably higher than some buyers might expect and vary according to household size and location.
For the York/Kittery Housing Market Area, which includes Berwick, Eliot, Kittery, South Berwick, and York, the income limits effective June 1, 2026 are:
- $132,900 for a household of one or two people
- $152,835 for households of three or more people
Elsewhere in York County, different limits may apply. For most York County communities outside the designated housing market areas, the current limits are $116,554 for one- or two-person households and $134,037 for households of three or more.
Because the applicable limit depends on the community where you plan to buy, buyers should confirm current eligibility with a MaineHousing-approved lender.
How Expensive a Home Can You Buy?
MaineHousing also establishes purchase-price limits.
For a one-unit home in York, Kittery, Eliot, Berwick and South Berwick, the current published purchase-price limit is $565,000. The same $565,000 limit applies to one-unit homes throughout most of York County.
Higher limits apply to qualifying owner-occupied multi-unit properties:
- Two units: $625,000
- Three units: $675,000
- Four units: $775,000
These figures are program eligibility ceilings—not an indication of how much an individual buyer should or will qualify to borrow. Mortgage qualification still depends on income, debt, credit, interest rates, and other underwriting factors.
The purchase-price limits are particularly relevant in Southern Maine, where home prices can vary dramatically from one neighborhood or property type to another.
What Credit Score Do You Need?
MaineHousing currently states that applicants need acceptable credit history and a minimum credit score of 640.
As a general guideline, MaineHousing also advises buyers to anticipate using no more than approximately 30% to 33% of income for the monthly mortgage payment. A participating lender ultimately determines qualification based on the buyer's complete financial circumstances.
For buyers who are not quite mortgage-ready, speaking with a lender early can be valuable. It may provide enough time to improve credit, reduce debt, or accumulate additional savings before making an offer.
What Is MaineHousing Advantage?
One of the program's most useful features for buyers who have adequate income but limited cash savings is called Advantage.
Advantage can currently provide $5,000 toward the cash needed at closing, including eligible down payment and closing costs.
Importantly, MaineHousing states that Advantage does not increase the mortgage amount, does not create a second mortgage, and does not carry an additional interest-rate charge.
To receive Advantage assistance, borrowers must complete an approved hoMEworks homebuyer education class before closing and make a minimum borrower contribution equal to 1% of the loan. The cost of the homebuyer education class can count toward that contribution.
For a buyer who can comfortably afford a mortgage payment but is struggling to accumulate enough cash for both a down payment and closing costs, this assistance can be particularly meaningful.
Can You Buy With Little or No Down Payment?
Potentially.
MaineHousing loans can be paired with various mortgage-insurance or government-backed financing programs.
Current options described by MaineHousing include:
- USDA Rural Development: potentially 0% down
- VA financing: potentially 0% down
- FHA financing: typically 3.5% down
Eligibility varies significantly among these programs, and not every property or borrower will qualify.
This is why buyers should discuss the complete financing structure with a MaineHousing-approved lender rather than assuming that the First Home Loan itself requires a particular down payment.
Current MaineHousing Mortgage Rates
Another significant benefit is access to MaineHousing's fixed-rate mortgage program.
As of October 1, 2026, MaineHousing lists its First Home Loan at:
5.950% with zero points, both with and without Advantage assistance.
A two-point option without Advantage is listed at 5.450%. Rates are subject to change, and buyers should always verify the rate available when they are ready to purchase.
A useful detail for buyers is that MaineHousing's rate is generally established when the participating lender reserves the mortgage after an executed Purchase and Sale Agreement—not simply when a buyer begins the loan application.
MaineHousing currently provides a free rate lock of up to 90 days for existing homes and 210 days for new construction, including newly sited modular and mobile homes.
Can You Buy a Fixer-Upper?
The program offers an option that can be especially valuable in Maine's older housing stock.
Through Purchase Plus Improvement, eligible buyers may finance the cost of purchasing a home and certain improvements through a single mortgage and closing.
MaineHousing currently allows eligible improvements ranging from $500 to $35,000, provided that the combined purchase price and improvement costs remain within applicable program limits.
For a buyer who finds a structurally sound home that needs updating—perhaps new flooring, energy improvements, or other repairs—this can potentially make a property worth considering that might otherwise be passed over.
In Southern Maine, where renovated homes can command substantial premiums, expanding a search to include homes needing manageable improvements can sometimes create additional opportunities.
Can You Buy a Two-Family or Multi-Unit Property?
Yes.
The First Home Loan Program can finance qualifying owner-occupied two-, three-, and four-unit properties.
MaineHousing's Multi-Unit Advantage program can also provide increased down-payment and closing-cost assistance:
- Two-unit property: $8,000
- Three-unit property: $11,000
- Four-unit property: $14,000
Buyers using Multi-Unit Advantage must meet additional requirements, including completing approved homebuyer and landlord education programs.
For some first-time buyers, purchasing a duplex and occupying one unit while renting the other can provide another path toward homeownership.
It is important, however, to evaluate maintenance expenses, landlord responsibilities, vacancy risk, and financing requirements—not simply anticipated rental income.
What Happens If You Lose Your Job?
One less widely known feature of MaineHousing financing is Maine HOPE—HomeOwnership Protection for unEmployment.
A MaineHousing borrower who is in good standing and becomes unemployed may qualify for assistance covering up to four mortgage payments, including property taxes and homeowners insurance.
The assistance becomes a junior mortgage lien with no interest and no monthly payments. It is generally repaid when the property is sold, the MaineHousing mortgage is paid off or the property stops being the borrower's primary residence.
While no buyer should purchase a home based on this protection alone, it provides an additional financial safeguard not found with every mortgage product.
Special Programs for Veterans and First-Generation Buyers
MaineHousing also offers programs that may provide additional assistance to specific buyers.
SaluteME
Active-duty, veteran and retired military personnel may qualify for MaineHousing's SaluteME program, which currently provides a 0.50 percentage-point discount from the standard First Home Loan 30-year fixed rate. Unlike the standard First Home Loan qualification, eligible military borrowers do not necessarily have to be first-time homeowners.
First Generation Program
Buyers who never lived in a home owned by their biological parents or legal guardians—or who spent time in foster care during childhood—may qualify for MaineHousing's First Generation Program, which can provide $10,000 toward down payment and closing costs.
Buyers who believe either program may apply to them should discuss eligibility directly with a participating lender.
What Types of Homes Qualify?
The First Home Loan Program can generally be used to purchase:
- New or existing single-family homes
- Condominiums
- Owner-occupied two- to four-unit buildings
- Certain permanently attached mobile homes built within the previous 20 years
Property-specific requirements and purchase-price limits still apply.
The home must generally be purchased as the buyer's primary residence, so this is not a financing program designed for vacation homes or investment-only properties.
How Do You Apply for a Maine First Home Loan?
The process begins with a MaineHousing-approved participating lender.
A lender can determine:
- Whether your household meets the income requirements.
- Whether you qualify as a first-time buyer under MaineHousing guidelines.
- Which mortgage program fits your financial circumstances.
- Whether Advantage or another assistance program is available.
- How much home you can realistically afford.
MaineHousing currently works with more than 40 participating lenders across the state.
For most buyers, getting pre-approved before beginning a serious home search is especially important. It allows you and your real estate agent to focus on properties that satisfy both your financial qualifications and MaineHousing's program requirements.
Why the First Home Loan Program Matters in Southern Maine
The greatest obstacle to homeownership is not always the monthly mortgage payment.
For many buyers, it is the combination of down payment, closing costs, and upfront cash requirements.
That can be particularly challenging in markets such as York and Kittery, where home values have risen substantially over the past several years.
The MaineHousing First Home Loan Program cannot solve every affordability challenge, but it can potentially reduce several of the financial barriers to purchasing a home.
And because the definition of a first-time homebuyer includes many people who previously owned a home, it is worth investigating even if you initially assume you would not qualify.
Thinking About Buying Your First Home in Southern Maine?
Buying a home involves much more than finding a property you like. Financing strategy, property eligibility, negotiation, and understanding local market conditions can all have a significant effect on the outcome.
If you are considering buying in York, Kittery, Ogunquit, Cape Neddick or elsewhere along the Southern Maine Seacoast, Great Seacoast Homes can help you understand the local market, identify appropriate properties, and coordinate your search with an experienced MaineHousing-approved lender.
Before ruling out homeownership because of the down payment or today's financing environment, it may be worth finding out exactly what programs are available to you.
For official eligibility requirements, current rates, and participating lenders, visit the MaineHousing First Home Loan Program.
Program requirements, income limits, purchase-price limits, and mortgage rates are subject to change. Great Seacoast Homes is not a mortgage lender. This article is provided for general informational purposes and should not be considered lending, financial, legal, or tax advice. Buyers should verify current eligibility and financing terms directly with MaineHousing and a participating lender.